Deadlines · 13 October 2026
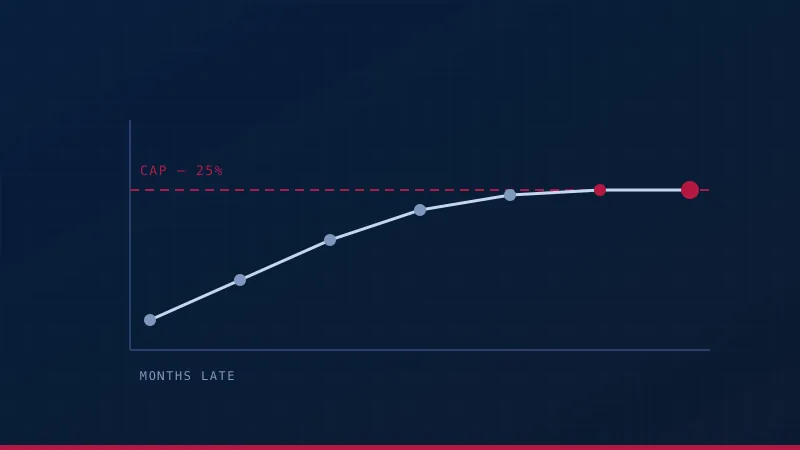
If you are owed a refund or owe nothing, there is no late-filing penalty at all. If you owe, the numbers are calculable — and usually smaller than they are imagined.
Filing rules · 11 October 2026
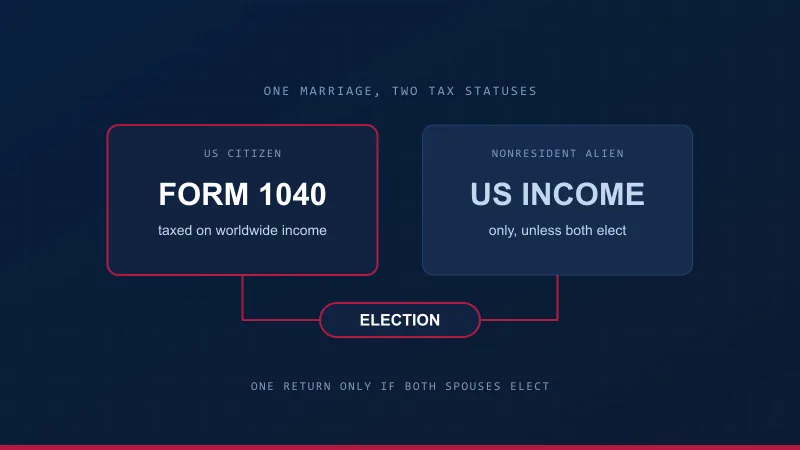
Separately by default, jointly by election, or as head of household. The choice turns on your spouse's income and assets, and the joint election cannot be made again once it ends.
Filing rules · 7 October 2026
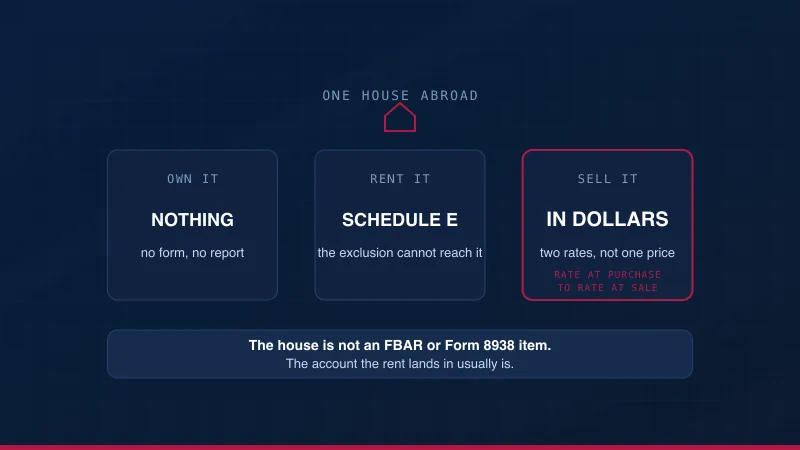
Owning it reports nothing. Renting it is Schedule E income the exclusion cannot touch, and a sale is measured in dollars — so a flat that broke even locally can still show a gain.
Filing rules · 7 October 2026
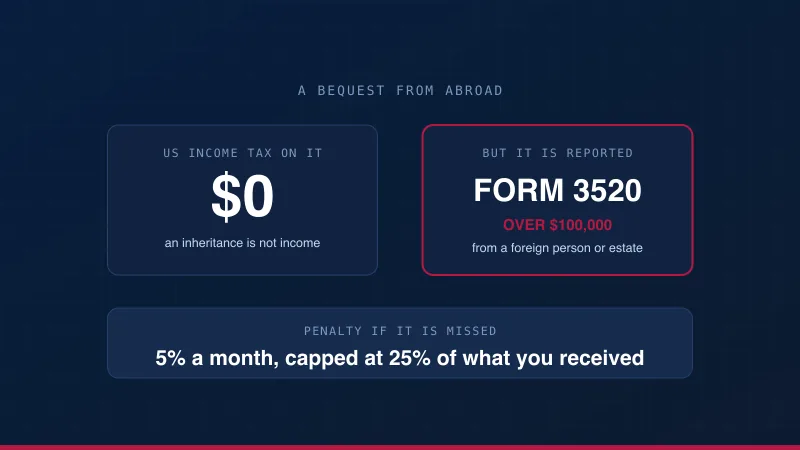
The inheritance is not income and carries no US tax. The reporting is where the cost sits — Form 3520 over $100,000, and a penalty that reaches a quarter of what you received.
Deadlines · 6 October 2026
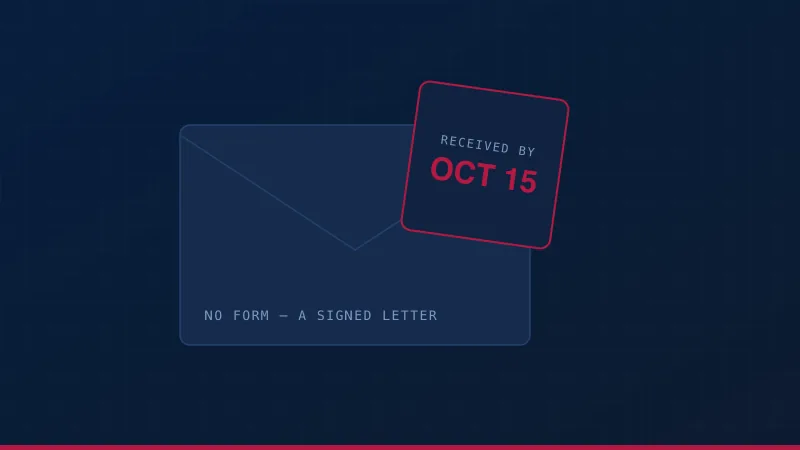
No form, no fee, and no approval notice: the IRS writes back only if the answer is no. What the letter has to contain, and what it does not cover.
Filing rules · 6 October 2026
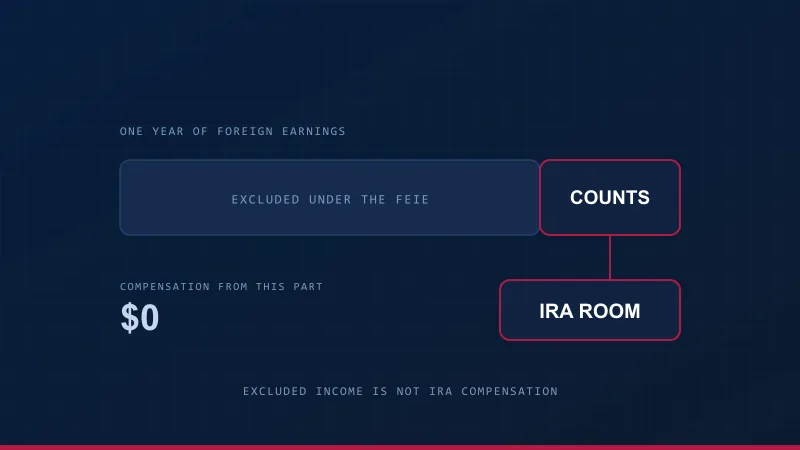
Only from taxable compensation — and income removed by the Foreign Earned Income Exclusion does not count. When the exclusion leaves you no room, and what a contribution made anyway costs.
FBAR · 30 September 2026
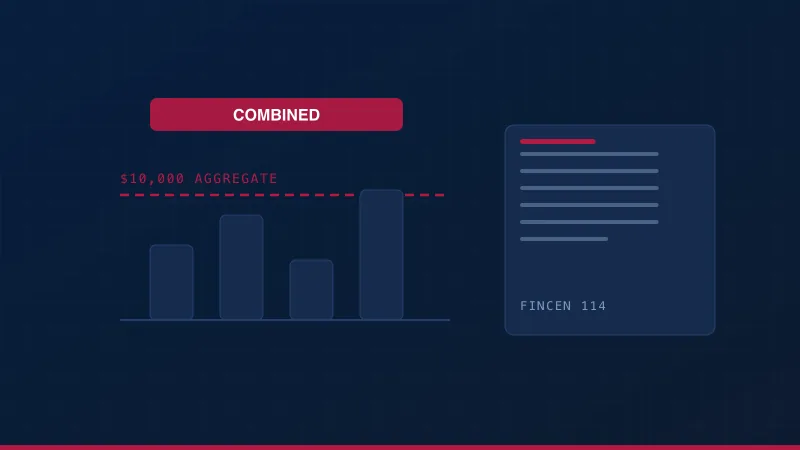
A separate filing, to a separate agency, with separate penalties — and since July 2026, without the written no-penalty promise that used to cover late filers.
Deadlines · 22 September 2026
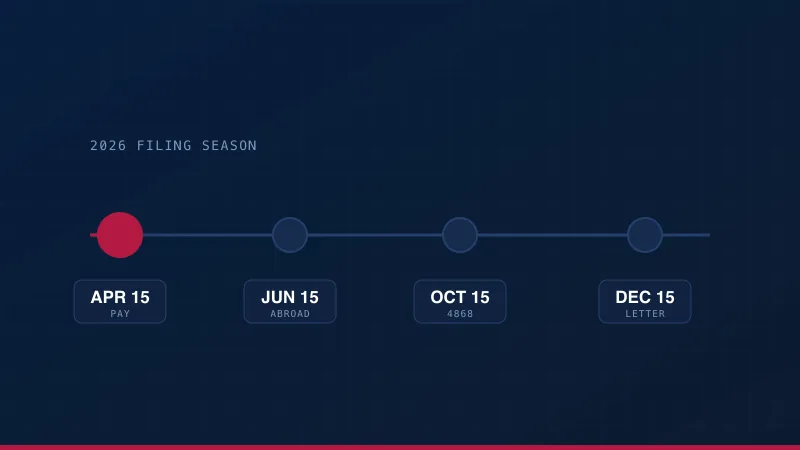
Four dates, and the one that applies depends on where you live, whether you extended, and whether you owe. The payment deadline is not one of the ones that moves.
Filing rules · 22 September 2026
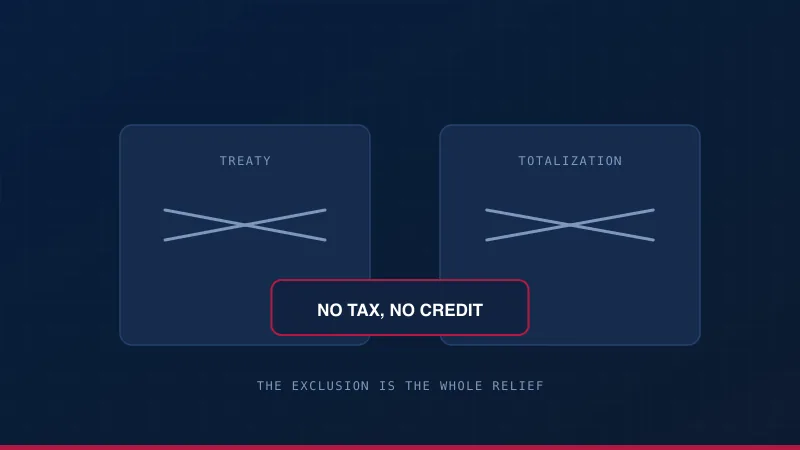
A light local charge sounds like good news and is mostly neutral: no Malaysian tax on US income means no credit, and above the exclusion the US collects.
Filing rules · 22 September 2026
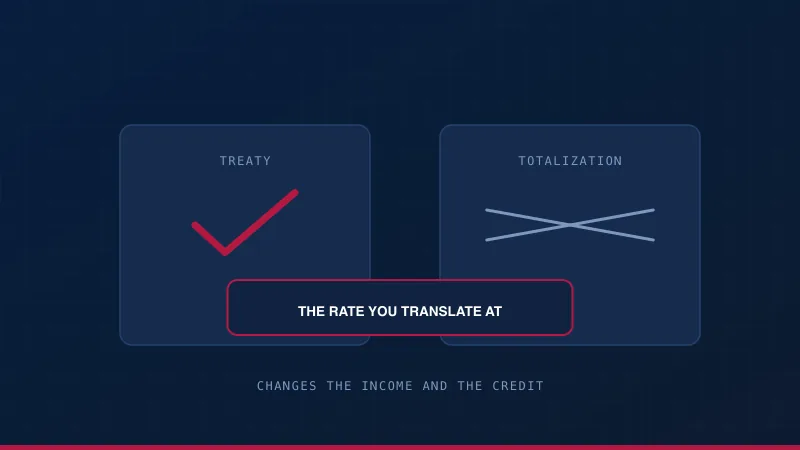
Currency translation is not a formality here. Which rate you use for income and for the tax paid changes the credit, and the answer has to be consistent.
Filing rules · 22 September 2026
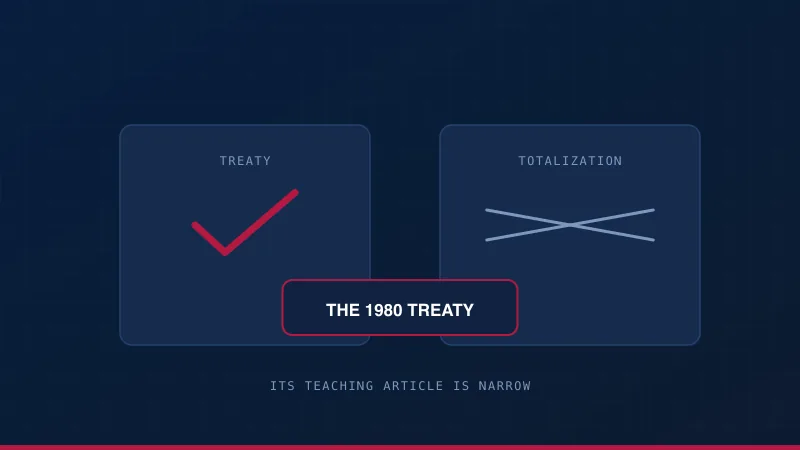
The treaty's teaching and research article is narrow and time-limited, not a general exemption. What actually costs money is Schedule SE.
Filing rules · 22 September 2026
The exit charge is the one to plan around: South Africa deems a disposal when you leave, and the US taxes the same gain when it is actually realised.
Filing rules · 22 September 2026
Everywhere else the treaty exists and the totalization agreement does not. Brazil is the inversion, so self-employment tax is relievable and the income tax side is bare.
Filing rules · 22 September 2026
Day 183 changes everything: Colombia starts taxing your US income, and there is no treaty to allocate between the two systems.
Filing rules · 22 September 2026
The mechanical questions have answers here. The judgement moves to pensions, dual nationality and which income category you are actually in.
Filing rules · 22 September 2026
The treaty settles the income tax. It cannot touch the self-employment charge, which is the whole liability for most Americans working from Bali or Jakarta.
Filing rules · 22 September 2026
The treaty defers an RRSP and does nothing at all for a TFSA. That gap is where most of the work on a Canadian return actually sits.
Filing rules · 22 September 2026
Signed is not in force. The 2004 totalization agreement provides nothing, whoever says otherwise — and Mexican residency turns on more than a day-count.
Filing rules · 22 September 2026
Territorial taxation is the whole story. No Costa Rican tax on US-source income means no credit, and the exclusion carries the return alone.
Filing rules · 22 September 2026
A TIEA is not a treaty. It improves transparency between two governments and gives you no residency article, no pension article and no relief.
Filing rules · 22 September 2026
The treaty handles the income tax. What it does not handle is the accounts: PFICs, PPF and EPF, and NRE interest that is exempt in India and taxable in America.
Filing rules · 22 September 2026
One of the oldest US treaties still in force. It relieves double income tax and carries almost none of the machinery a modern treaty would.
Filing rules · 22 September 2026
No treaty does not mean no credit. Form 1116 works on the statute; what is missing is everything a treaty would have added around it.
Filing rules · 22 September 2026
Rates moved. Any comparison of the exclusion against the credit built on pre-reform assumptions is answering a question that no longer exists.
Filing rules · 22 September 2026
Two Norwegian charges, two different answers: the bracket tax is creditable, the wealth tax is not. Keeping them apart is what makes Form 1116 right.
Filing rules · 22 September 2026
At roughly 52% combined the credit is not a close call. The scheme that lowers the Danish bill is what makes it one again.
Filing rules · 22 September 2026
The salary is straightforward. Super is not — it is tax-favoured in Australia and not clearly a pension for US treaty purposes.
Filing rules · 22 September 2026
A treaty relieves double income tax; only a totalization agreement relieves double social security. New Zealand has one and not the other.
Filing rules · 22 September 2026
Signed is not in force, here as elsewhere. And a Polish exemption that removes Polish tax does not remove US tax — it just removes the credit that would have covered it.
Filing rules · 22 September 2026
In a 45% country the credit almost always wins. At 15% and 23% it often does not, and claiming it can leave US tax the exclusion would have removed.
Filing rules · 22 September 2026
The salary side is straightforward at Swedish rates. The ISK is not: Sweden taxes a deemed return, the US taxes the real one, and a treaty does not bridge that.
Filing rules · 22 September 2026
Two Americans on identical salaries in different cantons pay different Swiss tax, and therefore carry different US credits. The canton is a US tax decision.
Filing rules · 22 September 2026
Splitting the payslip correctly is most of the work on an Irish return: USC belongs on Form 1116, PRSI belongs to the totalization agreement.
Filing rules · 22 September 2026
NHR closed; a narrower incentive replaced it. Which regime you are under decides your Portuguese rate, and your Portuguese rate decides your credit.
Filing rules · 22 September 2026
The counter-intuitive one: a regime that saves Spanish tax can cost American tax, because the credit is limited to what you actually paid abroad.
Filing rules · 22 September 2026
Reduced Italian tax means a reduced credit on Form 1116. The regimes are still worth having; they are not worth assuming.
Filing rules · 22 September 2026
The ruling moves tax rather than removing it: exempting salary from Dutch tax shrinks the foreign tax credit, and the rate itself changes in 2027.
Filing rules · 22 September 2026
The treaty handles the salary. What it does not handle is the ISA, the 25% tax-free lump sum, or a tax year that starts in April while the US one starts in January.
Filing rules · 22 September 2026
At German effective rates the credit is rarely a close call. The items worth attention are church tax, which is creditable, and the pension products, which are not what they look like.
Filing rules · 22 September 2026
One of the few genuinely retrospective wins in expat tax sits in France: CSG and CRDS are creditable, and years still open can be corrected.
Filing rules · 22 September 2026
A treaty without a totalization agreement, which leaves 15.3% standing on every dollar a remote worker earns — and a Thai remittance rule that changed what gets taxed here.
Filing rules · 22 September 2026
No treaty, no totalization agreement, and rates low enough that the exclusion generally wins — which is the opposite of the advice that travels with people from Europe.
Filing rules · 22 September 2026
Signed is not in force. Until ratification completes there is no treaty position, no reduced withholding and no tie-breaker — only the ordinary foreign tax credit.
Filing rules · 22 September 2026
A treaty and a totalization agreement, rates high enough that Form 1116 normally wins, and a tax-free Japanese wrapper that is nothing of the sort on the US return.
Filing rules · 22 September 2026
A treaty, a totalization agreement, and two decisions that actually move the number: the 19% flat election, and whether the credit or the exclusion fits your year.
Filing rules · 22 September 2026
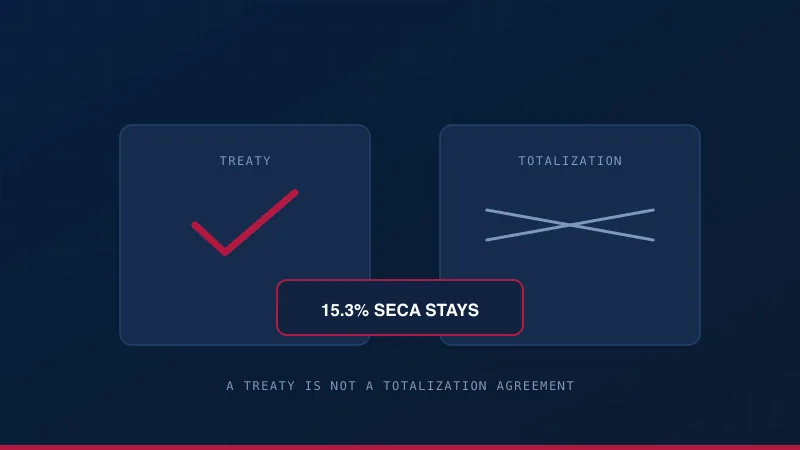
A treaty relieves double income tax; only a totalization agreement relieves double social security — and China has the first without the second.
Filing rules · 22 September 2026
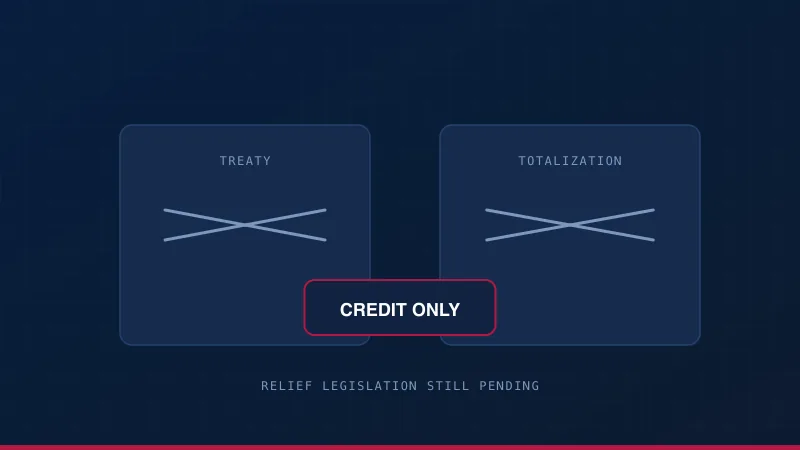
No treaty, no totalization agreement, and relief that would arrive by legislation rather than by treaty — so Form 1116 is the whole of the machinery.
Filing rules · 22 September 2026
No treaty and no totalization agreement, and every allowance in a Doha package is pay on the US return — which is what pushes a comfortable salary past the exclusion.
Filing rules · 22 September 2026
No treaty and no totalization agreement, and the deduction on your payslip is insurance rather than income tax — so the exclusion carries the return with nothing held in reserve.
Filing rules · 22 September 2026
No treaty and no totalization agreement, and no Omani income tax until 2028 — which makes the exclusion-versus-credit decision you take now a five-year one.
Filing rules · 21 September 2026
No treaty and no totalization agreement, so the exclusion and the housing exclusion carry the return — and self-employment tax still applies in full, combat zone or not.
Filing rules · 21 September 2026
Zero personal income tax means nothing to credit — the exclusion and the housing exclusion do the work, and a free-zone company brings Form 5471 into the picture.
Filing rules · 21 September 2026
No treaty, no totalization agreement, and no local income tax — the exclusion carries the return, and the end-of-service benefit is the item most often mistimed.
Filing rules · 20 September 2026
The treaty credits Bangladeshi income tax, but self-employment tax still applies in full to the NGO and development-sector consultants who make up so much of this group.
Filing rules · 20 September 2026
The treaty credits Moroccan income tax, but self-employment tax still applies in full to freelancers and remote workers — and at 37%, the credit usually beats the exclusion for employees.
Deadlines · 15 September 2026
What is due on the date, whether you can extend past it, what your foreign accounts owe, and what happens if it passes without you filing.
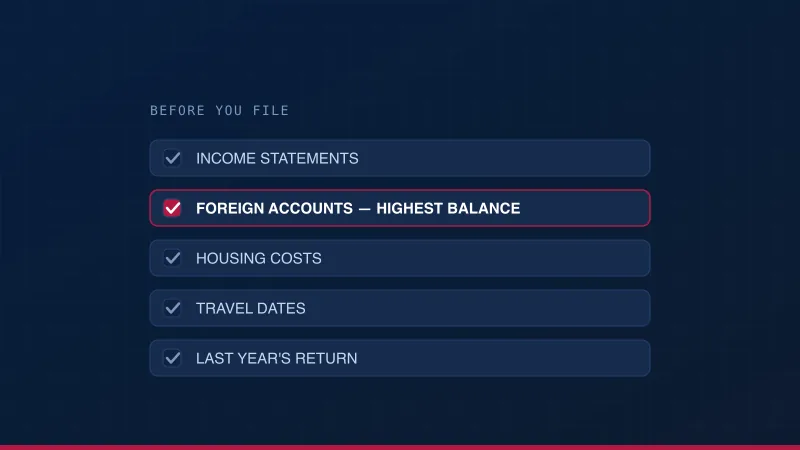
Filing rules · 15 September 2026
A complete return takes about two weeks once the documents are complete, and considerably longer when they arrive one at a time.
Filing rules · 11 September 2026
Most years, preparation is enough. Advisory work earns its fee when a decision is still open — a move, a new foreign account, an election that binds for five years.
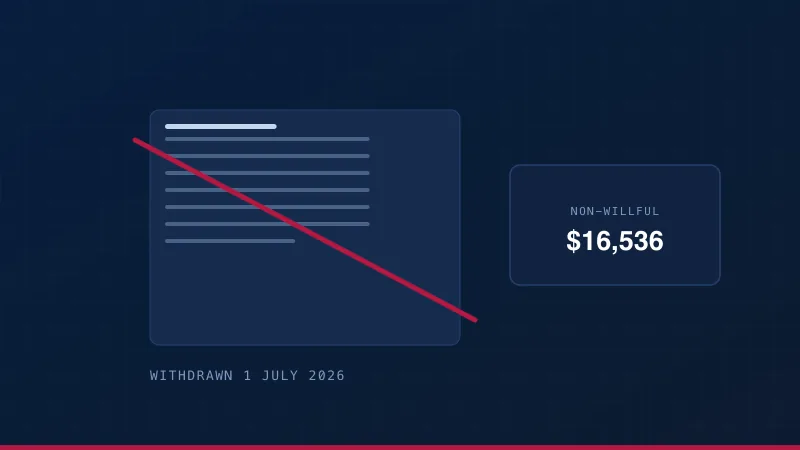
Rule changes · 1 July 2026
The IRS terminated the procedure around 1 July 2026. Late FBARs now travel with a Streamlined submission or a reasonable-cause statement — and the non-willful penalty stays at $16,536, because the 2026 inflation increase was cancelled by OMB M-26-11.
Filing rules · 20 March 2025
What you file, when it is due, and which forms attach — with each figure carrying its tax year.
Residency · 20 March 2025
Who is a nonresident alien for tax purposes, and what that changes on the return.
Residency · 20 March 2025
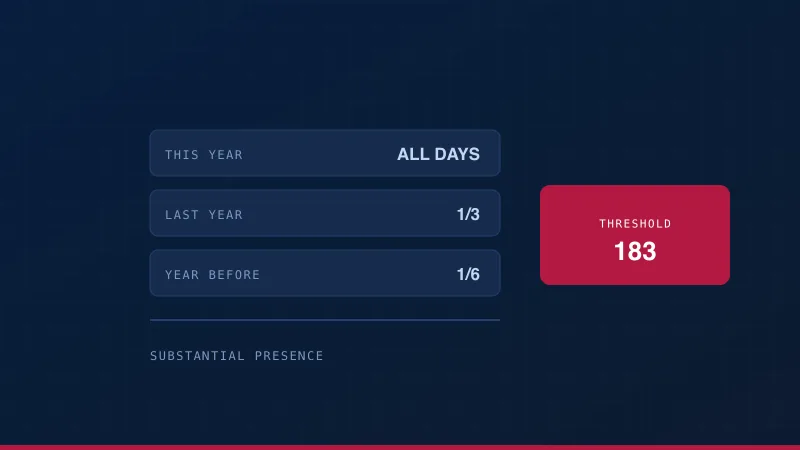
The substantial presence test, the green-card test, and the returns each one produces.
State tax · 20 March 2025
Why leaving the country does not always end a state filing obligation, and what breaks it.
Digital nomads · 20 March 2025
Moving every few months makes the physical presence test the hard part, not the income.
Filing rules · 20 March 2025
The exclusion, the housing exclusion, the credit, timing, retirement accounts and state residency.
 Read the piece